Pearson Edexcel · A-Level · Economics B
Course version: 9EB0 · Version from Sept 2015
C) Statement of comprehensive income (profit and loss account)
Full specification wording
Profit and loss: c) Statement of comprehensive income (profit and loss account)
The statement of comprehensive income, traditionally known as the profit and loss account, is a fundamental financial document summarising a business's revenues, costs, and expenses over a…
Checked against the Pearson Edexcel 9EB0 specification (opens in a new tab) on .
- Point 3 of 4
- 3 key terms
Study notes
From the checked teaching notes for this specification point.
The idea
The statement of comprehensive income, traditionally known as the profit and loss account, is a fundamental financial document summarising a business's revenues, costs, and expenses over a specific period. It illustrates how revenue is transformed into net income by sequentially deducting the cost of sales to find gross profit, removing operating expenses to determine operating profit, and subtracting interest and tax to calculate profit for the year. For example, a retailer generating £500,000 in sales revenue will deduct the £200,000 cost of purchasing inventory to reveal a £300,000 gross profit, before subtracting rent and wages to find the operating profit. This statement is vital for stakeholders assessing financial performance.
What earns the marks
- Identify the purpose of the statement of comprehensive income as showing financial performance over a period.
- Recognise the sequence of deductions: revenue minus cost of sales equals gross profit.
- Understand that operating profit is calculated by deducting operating expenses from gross profit.
- Recall that profit for the year (net profit) is found by deducting interest and taxation from operating profit.
Common mistakes and how to put them right
Confusing the statement of comprehensive income with the statement of financial position.
Put it right: The former covers a period of time while the latter is a snapshot at a specific date.
Forgetting to deduct the cost of sales before calculating operating profit.
Put it right: Calculate gross profit first by subtracting cost of sales from revenue.
Treating capital expenditure as an expense in the profit and loss account.
Put it right: Ensure only revenue expenditure (day-to-day running costs) is included here.
Exam tips
- Memorise the exact structure and order of the statement of comprehensive income to quickly navigate calculation questions.
- Pay close attention to the time period stated in the question, as revenues and expenses must match this exact duration.
- Use the figures provided in a stimulus to construct a mini profit and loss account if asked to calculate a specific profit figure.
Try the lesson
The start of the Profit and loss: c) Statement of comprehensive income (profit and loss account) lesson, made from checked teaching notes for this specification point.
Have a go first
What is the primary purpose of a firm's statement of comprehensive income?
Listen
The statement of comprehensive income, traditionally known as the profit and loss account, is a fundamental financial document summarising a business's revenues, costs, and expenses over a specific period. It illustrates how revenue is transformed into net income by sequentially deducting the cost of sales to find gross profit, removing operating expenses to determine operating profit, and subtracting interest and tax to calculate profit for the year. For example, a retailer generating £500,000 in sales revenue will deduct the £200,000 cost of purchasing inventory to reveal a £300,000 gross profit, before subtracting rent and wages to find the operating profit. This statement is vital for stakeholders assessing financial performance. A strong answer earns marks for these points. Identify the purpose of the statement of comprehensive income as showing financial performance over a period. Recognise the sequence of deductions: revenue minus cost of sales equals gross profit. Understand that operating profit is calculated by deducting operating expenses from gross profit. Recall that profit for the year (net profit) is found by deducting interest and taxation from operating profit. Exam tip: Memorise the exact structure and order of the statement of comprehensive income to quickly navigate calculation questions.
See it

Put it in order
Put these steps in the order they happen.
- 1. Profit for the year
- 2. Deduct interest and taxation
- 3. Gross profit
- 4. Operating profit
- 5. Revenue
- 6. Deduct cost of sales
- 7. Deduct operating expenses
Key words
Say what each word means before you turn the card.
Financial performance
Try answering aloud or in your head before turning the card.
Revenue and costs
Try answering aloud or in your head before turning the card.
Profitability
Try answering aloud or in your head before turning the card.
See every definition
- Financial performance
- What the statement of comprehensive income shows over a period, making it vital for stakeholders assessing a business.
- Revenue and costs
- The revenues, costs and expenses summarised over a specific period, with revenue transformed into net income by sequential deductions.
- Profitability
- Gross profit, operating profit and profit for the year, found by deducting cost of sales, operating expenses, interest and tax in turn.
Label the diagram
Some boxes have lost their names. Pick the right name for each number.
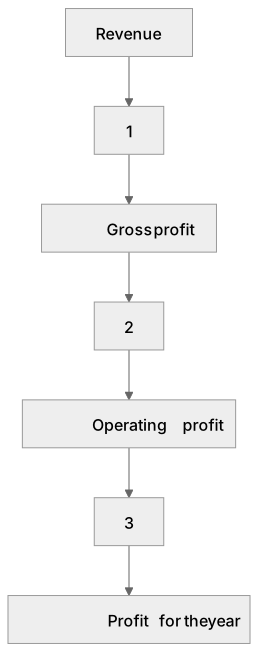
1Box 1
2Box 2
3Box 3
There is more to this lesson
The full lesson goes on to check your understanding and help you earn the marks. Create a free account to carry on, with your progress saved.
A week of Premium from your first lesson · Then the free plan continues · No card, no charge
Test your understanding of Profit and loss: c) Statement of comprehensive income (profit and loss account)
Active recall beats re-reading. Take an instant quiz now to test what you’ve learned and lock it into long-term memory.
A week of Premium from your first lesson · Then the free plan continues · No card, no charge