AQA · GCSE · Business
Course version: 8132 · Version from Sept 2017
Financial terms and calculations: Break-even
Break-even is the level of output at which total revenue equals total costs, so the business makes neither profit nor loss.
Checked against the AQA 8132 specification (opens in a new tab) on .
- Point 4 of 10
- 4 key terms
Study notes
From the checked teaching notes for this specification point.
The idea
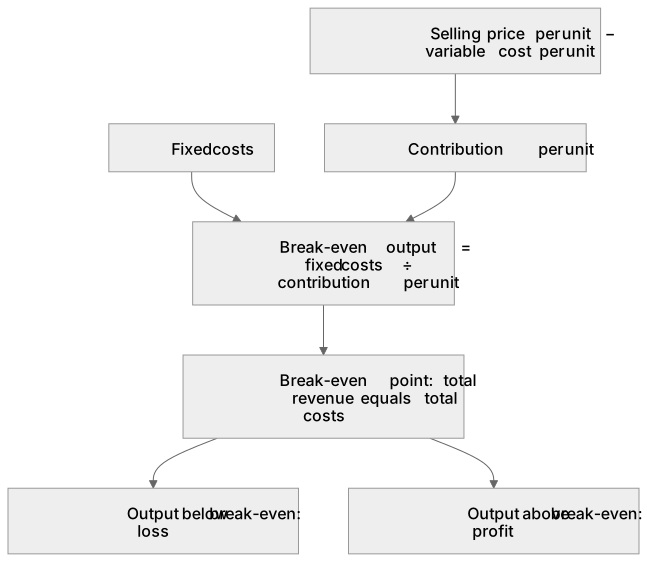
Break-even is the level of output at which total revenue equals total costs, so the business makes neither profit nor loss. It can be calculated using the formula: break-even output = fixed costs ÷ (selling price per unit − variable cost per unit). The denominator is the contribution per unit. For example, fixed costs are £10,000, selling price is £20 and variable cost per unit is £12. Contribution per unit is £20 − £12 = £8. Break-even output is £10,000 ÷ £8 = 1,250 units. On a break-even chart, the break-even point is where the total revenue line crosses the total cost line; output below this point results in a loss, and output above it results in a profit. Break-even analysis assumes costs and revenue behave linearly and that all output is sold, so it is a simplification.
What earns the marks
- State that break-even occurs where total revenue equals total costs, meaning zero profit and zero loss.
- Calculate contribution per unit as selling price per unit minus variable cost per unit.
- Calculate break-even output by dividing fixed costs by contribution per unit.
- Interpret a break-even chart by identifying the point where the total revenue line intersects the total cost line.
- Explain that output below break-even results in a loss and output above break-even results in a profit.
- Recognise that break-even analysis assumes linear costs and revenue and that all output is sold.
Common mistakes and how to put them right
Subtracting variable cost per unit from fixed costs instead of from selling price.
Put it right: Contribution per unit = selling price per unit − variable cost per unit.
Dividing contribution per unit by fixed costs.
Put it right: Break-even output = fixed costs ÷ contribution per unit.
Confusing break-even output with break-even revenue.
Put it right: Break-even output is in units, while break-even revenue is break-even output multiplied by selling price per unit.
Exam tips
- Write down the formula before substituting values to make your method clear.
- Check that fixed costs and contribution per unit are in the same currency units before dividing.
- When interpreting a chart, label the break-even point and state the output and revenue at that point.
Try the lesson
The start of the Financial terms and calculations: Break-even lesson, made from checked teaching notes for this specification point.
Have a go first
A business sells its product for £20 per unit. Variable costs are £12 per unit and fixed costs are £4,000. What is the break-even level of output?
Listen
Break-even is the level of output at which total revenue equals total costs, so the business makes neither profit nor loss. It can be calculated using the formula: break-even output = fixed costs ÷ (selling price per unit − variable cost per unit). The denominator is the contribution per unit. For example, fixed costs are £10,000, selling price is £20 and variable cost per unit is £12. Contribution per unit is £20 − £12 = £8. Break-even output is £10,000 ÷ £8 = 1,250 units. On a break-even chart, the break-even point is where the total revenue line crosses the total cost line; output below this point results in a loss, and output above it results in a profit. Break-even analysis assumes costs and revenue behave linearly and that all output is sold, so it is a simplification. A strong answer earns marks for these points. State that break-even occurs where total revenue equals total costs, meaning zero profit and zero loss. Calculate contribution per unit as selling price per unit minus variable cost per unit. Calculate break-even output by dividing fixed costs by contribution per unit. Interpret a break-even chart by identifying the point where the total revenue line intersects the total cost line. A common slip: Subtracting variable cost per unit from fixed costs instead of from selling price. Instead, contribution per unit = selling price per unit − variable cost per unit. Exam tip: Write down the formula before substituting values to make your method clear.
See it
Key words
Say what each word means before you turn the card.
Break-even
Try answering aloud or in your head before turning the card.
Contribution per unit
Try answering aloud or in your head before turning the card.
Break-even output
Try answering aloud or in your head before turning the card.
Break-even chart
Try answering aloud or in your head before turning the card.
See every definition
- Break-even
- The level of output at which total revenue equals total costs, so the business makes neither profit nor loss.
- Contribution per unit
- The selling price per unit minus the variable cost per unit, which is the denominator in the break-even formula.
- Break-even output
- Fixed costs divided by the contribution per unit.
- Break-even chart
- A chart on which the break-even point is where the total revenue line crosses the total cost line.
Label the diagram
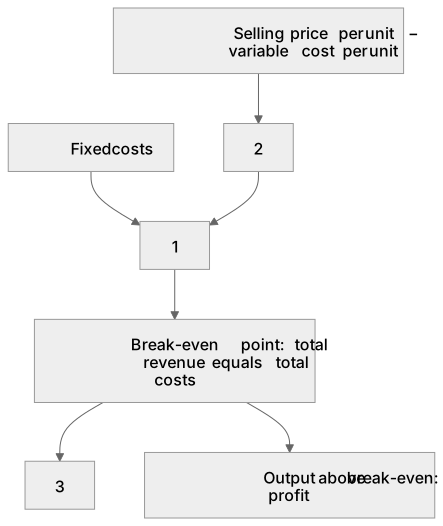
Some boxes have lost their names. Pick the right name for each number.
1Box 1
2Box 2
3Box 3
There is more to this lesson
The full lesson goes on to check your understanding and help you earn the marks. Create a free account to carry on, with your progress saved.
A week of Premium from your first lesson · Then the free plan continues · No card, no charge
Test your understanding of Financial terms and calculations: Break-even
Active recall beats re-reading. Take an instant quiz now to test what you’ve learned and lock it into long-term memory.
A week of Premium from your first lesson · Then the free plan continues · No card, no charge