AQA · GCSE · Business
Course version: 8132 · Version from Sept 2017
The concept of quality: inspection costs
Inspection costs are the expenses a business incurs when checking that products or services meet quality standards before they reach customers.
Checked against the AQA 8132 specification (opens in a new tab) on .
- Point 10 of 13
- 4 key terms
Study notes
From the checked teaching notes for this specification point.
The idea
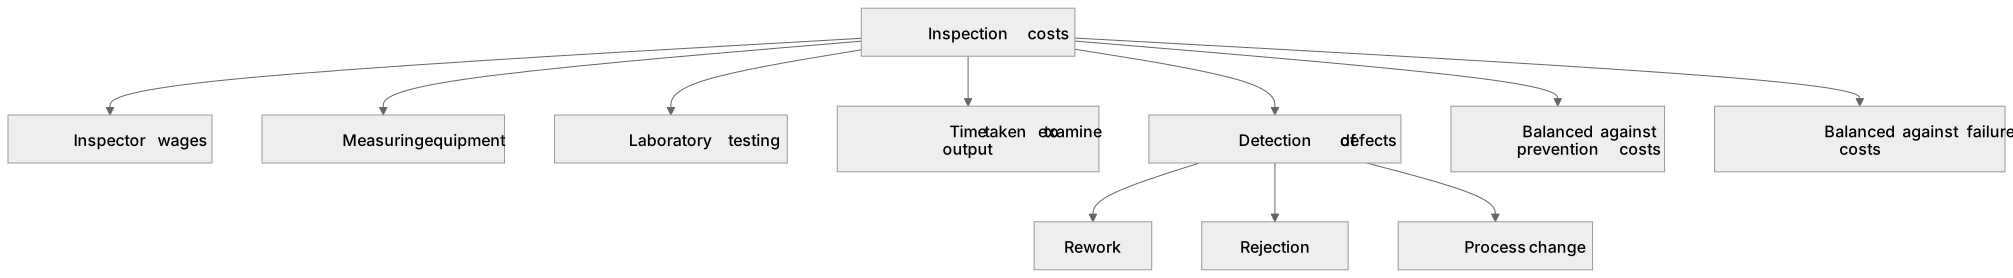
Inspection costs are the expenses a business incurs when checking that products or services meet quality standards before they reach customers. They include paying inspectors, buying and maintaining measuring equipment, laboratory testing, and the time taken to examine output. For example, a clothing manufacturer might pay staff to check every batch of shirts for stitching faults, measure collar sizes against a specification, and record results. Inspection can catch defects before sale, protecting reputation and reducing returns, but it does not create quality; it only identifies problems after they have occurred. Inspection costs therefore form part of a business's wider quality approach and must be balanced against prevention costs, such as training and better processes, and failure costs, such as refunds and lost goodwill.
What earns the marks
- Defines inspection costs as the money spent on checking that goods or services meet quality standards.
- Identifies examples such as inspector wages, testing equipment, laboratory fees and the time cost of checking output.
- Explains that inspection detects defects after production rather than preventing them from occurring.
- Links inspection costs to wider quality management, including the trade-off with prevention and failure costs.
- Uses a concrete business example, such as a manufacturer checking garments or a restaurant checking food portions, to show how inspection costs arise.
Common mistakes and how to put them right
Confusing inspection costs with prevention costs.
Put it right by stating that inspection is a detection activity, not a prevention activity.
Assuming inspection always improves quality.
Put it right: Still requires action. Correct by explaining that inspection must be followed by rework, rejection or process change.
Treating inspection costs as only the inspector's wages.
Put it right by listing several cost categories.
Exam tips
- Anchor your answer in a named business context so inspection costs are concrete rather than abstract.
- Use the chain of reasoning: inspection cost leads to detection, which leads to a decision about rework, rejection or process improvement.
- When evaluating, weigh inspection costs against the cost of poor quality, such as refunds, recalls and damaged reputation.
Try the lesson
The start of the The concept of quality: inspection costs lesson, made from checked teaching notes for this specification point.
Have a go first
What is meant by inspection costs in the context of quality?
Listen
Inspection costs are the expenses a business incurs when checking that products or services meet quality standards before they reach customers. They include paying inspectors, buying and maintaining measuring equipment, laboratory testing, and the time taken to examine output. For example, a clothing manufacturer might pay staff to check every batch of shirts for stitching faults, measure collar sizes against a specification, and record results. Inspection can catch defects before sale, protecting reputation and reducing returns, but it does not create quality; it only identifies problems after they have occurred. Inspection costs therefore form part of a business's wider quality approach and must be balanced against prevention costs, such as training and better processes, and failure costs, such as refunds and lost goodwill. A strong answer earns marks for these points. Defines inspection costs as the money spent on checking that goods or services meet quality standards. Identifies examples such as inspector wages, testing equipment, laboratory fees and the time cost of checking output. Explains that inspection detects defects after production rather than preventing them from occurring. Links inspection costs to wider quality management, including the trade-off with prevention and failure costs. A common slip: Confusing inspection costs with prevention costs: inspection checks existing output, while prevention stops defects arising in the first place. Instead, stating that inspection is a detection activity, not a prevention activity. Exam tip: Anchor your answer in a named business context so inspection costs are concrete rather than abstract.
See it
Key words
Say what each word means before you turn the card.
Inspection costs
Try answering aloud or in your head before turning the card.
Quality management
Try answering aloud or in your head before turning the card.
Prevention costs
Try answering aloud or in your head before turning the card.
Failure costs
Try answering aloud or in your head before turning the card.
See every definition
- Inspection costs
- The expenses a business incurs when checking that products or services meet quality standards before they reach customers.
- Quality management
- A business's wider quality approach, in which inspection costs must be balanced against prevention costs and failure costs.
- Prevention costs
- Costs such as training and better processes that stop defects arising in the first place, rather than detecting them afterwards.
- Failure costs
- Costs such as refunds and lost goodwill that arise when quality problems are not prevented or detected.
Label the diagram
Some boxes have lost their names. Pick the right name for each number.
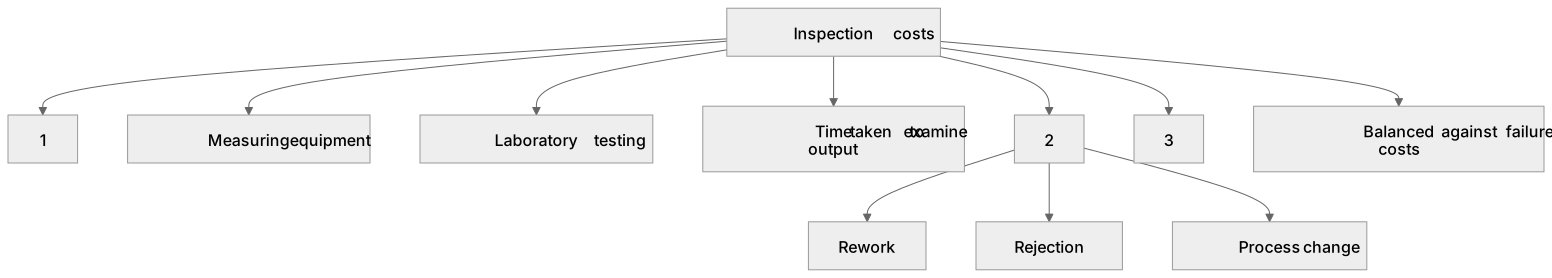
1Box 1
2Box 2
3Box 3
There is more to this lesson
The full lesson goes on to check your understanding and help you earn the marks. Create a free account to carry on, with your progress saved.
A week of Premium from your first lesson · Then the free plan continues · No card, no charge
Test your understanding of The concept of quality: inspection costs
Active recall beats re-reading. Take an instant quiz now to test what you’ve learned and lock it into long-term memory.
A week of Premium from your first lesson · Then the free plan continues · No card, no charge