AQA · A-Level · Business
Course version: 7132 · Version from Sept 2023
Analysing financial performance: The value of break-even analysis
It is cheap, quick and persuasive, which is why a bank asks for it with a start-up loan application and why an operations manager uses it to test whether a new product can carry the fixed costs it…
- Point 5 of 8
- 4 key terms
Study notes
From the teaching notes for this specification point.
The idea
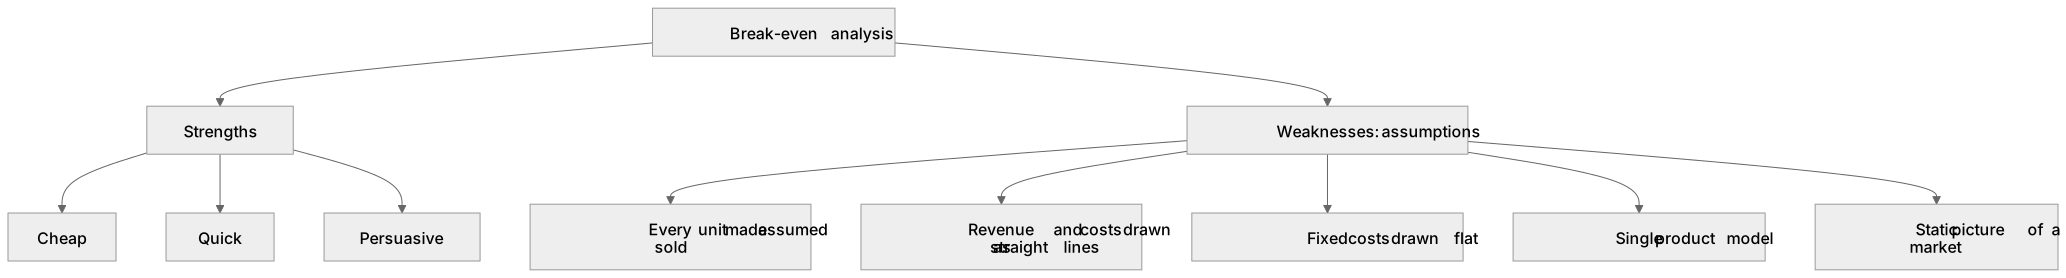
It is cheap, quick and persuasive, which is why a bank asks for it with a start-up loan application and why an operations manager uses it to test whether a new product can carry the fixed costs it brings with it. The weakness is in the assumptions. Every unit made is assumed sold, so unsold inventory does not exist on the chart; revenue and costs are drawn as straight lines, so a bulk discount on materials and a markdown to shift the last few hundred units both vanish; and fixed costs are drawn flat when in reality they step up as soon as another supervisor or another unit of warehouse space is needed. It is also a single product model, so a firm selling a range has to apportion fixed costs by judgement, and it is a static picture of a market that will not hold still.
What earns the marks
- Naming the decision the analysis actually supports for this firm, such as whether to launch, what to charge, or how much to borrow.
- Identifying a specific assumption and showing why it bites in this case, for example stepped fixed costs where the firm is close to needing a second unit.
- Using margin of safety as the risk measure and relating it to how volatile demand looks in the extract.
- Comparing break-even with an alternative tool such as a cash flow forecast or investment appraisal and saying what each adds.
- Reaching a judgement on how much weight the decision should place on the chart, rather than declaring the technique good or bad.
Common mistakes and how to put them right
Dismissing break-even as just a theory without naming a single assumption that fails here.
Believing break-even shows whether a product will sell, when it only shows how many must sell.
Confusing the break-even point with a target, so the answer treats reaching it as success rather than as the point where losses stop.
Ignoring the quality of the cost and price data the chart is built from, which is usually the weakest link in a start-up plan.
Exam tips
- This is asked as assess the value or evaluate the usefulness, and the marks sit in the limitations applied to the case, not in a memorised list.
- Anchor the judgement in how stable the firm costs and prices are, since break-even is strongest where both hold steady.
- A conclusion that says the chart is a useful starting point but should be tested against a cash flow forecast reads far better than one that says break-even is unrealistic.
Try the lesson
The start of the Analysing financial performance: The value of break-even analysis lesson, made from teaching notes for this specification point.
Have a go first
A business has break-even output of 4,000 units and current output of 5,000 units. What is its margin of safety?
Listen
It is cheap, quick and persuasive, which is why a bank asks for it with a start-up loan application and why an operations manager uses it to test whether a new product can carry the fixed costs it brings with it. The weakness is in the assumptions. Every unit made is assumed sold, so unsold inventory does not exist on the chart; revenue and costs are drawn as straight lines, so a bulk discount on materials and a markdown to shift the last few hundred units both vanish; and fixed costs are drawn flat when in reality they step up as soon as another supervisor or another unit of warehouse space is needed. It is also a single product model, so a firm selling a range has to apportion fixed costs by judgement, and it is a static picture of a market that will not hold still. A strong answer earns marks for these points. Naming the decision the analysis actually supports for this firm, such as whether to launch, what to charge, or how much to borrow. Identifying a specific assumption and showing why it bites in this case, for example stepped fixed costs where the firm is close to needing a second unit. Using margin of safety as the risk measure and relating it to how volatile demand looks in the extract. Comparing break-even with an alternative tool such as a cash flow forecast or investment appraisal and saying what each adds. Exam tip: This is asked as assess the value or evaluate the usefulness, and the marks sit in the limitations applied to the case, not in a memorised list.
See it
Key words
Say what each word means before you turn the card.
linearity assumption
Try answering aloud or in your head before turning the card.
stepped fixed costs
Try answering aloud or in your head before turning the card.
single product limitation
Try answering aloud or in your head before turning the card.
risk measurement
Try answering aloud or in your head before turning the card.
See every definition
- linearity assumption
- Revenue and costs are drawn as straight lines, so a bulk discount on materials and a markdown to shift the last few hundred units both vanish.
- stepped fixed costs
- Fixed costs are drawn flat when in reality they step up as soon as another supervisor or another unit of warehouse space is needed.
- single product limitation
- A firm selling a range has to apportion fixed costs by judgement because the model covers only one product.
- risk measurement
- Margin of safety is used as the risk measure and related to how volatile demand looks in the extract.
Label the diagram
Some boxes have lost their names. Pick the right name for each number.
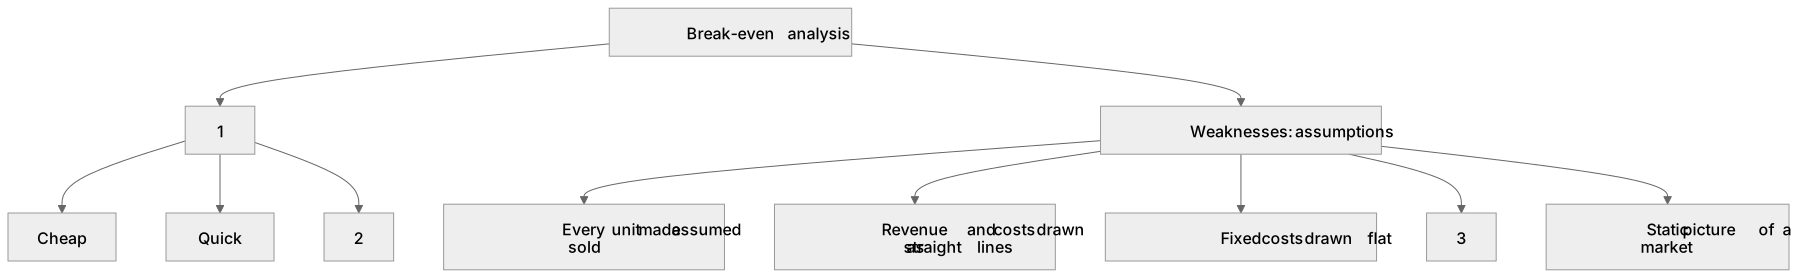
1Box 1
2Box 2
3Box 3
There is more to this lesson
The full lesson goes on to check your understanding and help you earn the marks. Create a free account to carry on, with your progress saved.
A week of Premium from your first lesson · Then the free plan continues · No card, no charge
Test your understanding of Analysing financial performance: The value of break-even analysis
Active recall beats re-reading. Take an instant quiz now to test what you’ve learned and lock it into long-term memory.
A week of Premium from your first lesson · Then the free plan continues · No card, no charge